



Live News
NUJ FCT COUNCIL WINS GOLD MEDAL AT 8TH NIGERIA-CHINA TABLE TENNIS FRIENDSHIP TOURNAMENT 2026
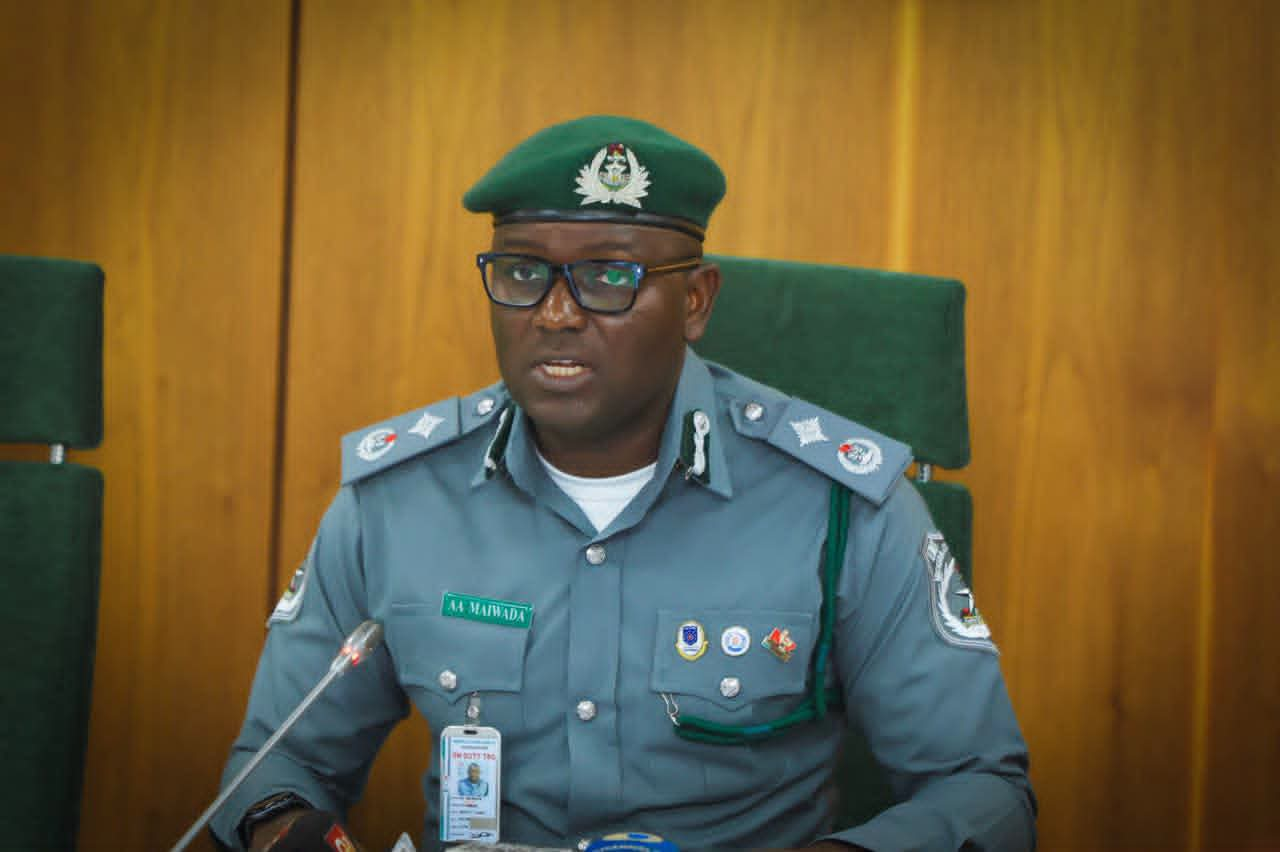
Nigeria Customs Generates ₦1.42trn, Processes 99,839 Goods Declarations in Two Months – Maiwada
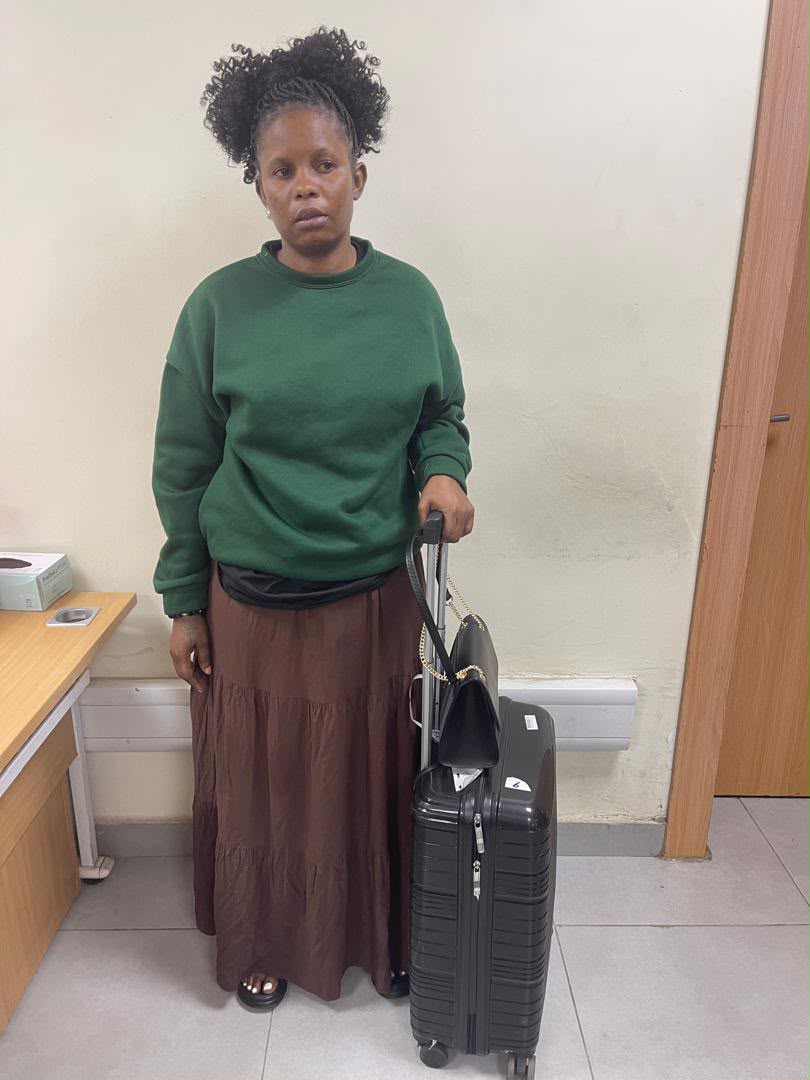
NDLEA Nabs Ugandan Church Visitor With 87 Wraps Of Cocaine Strapped To Private Part At Lagos Airport
21 dead after migrant boat capsizes off Senegal
Israel’s President picks Netanyahu’s rival Eisenkot to form government
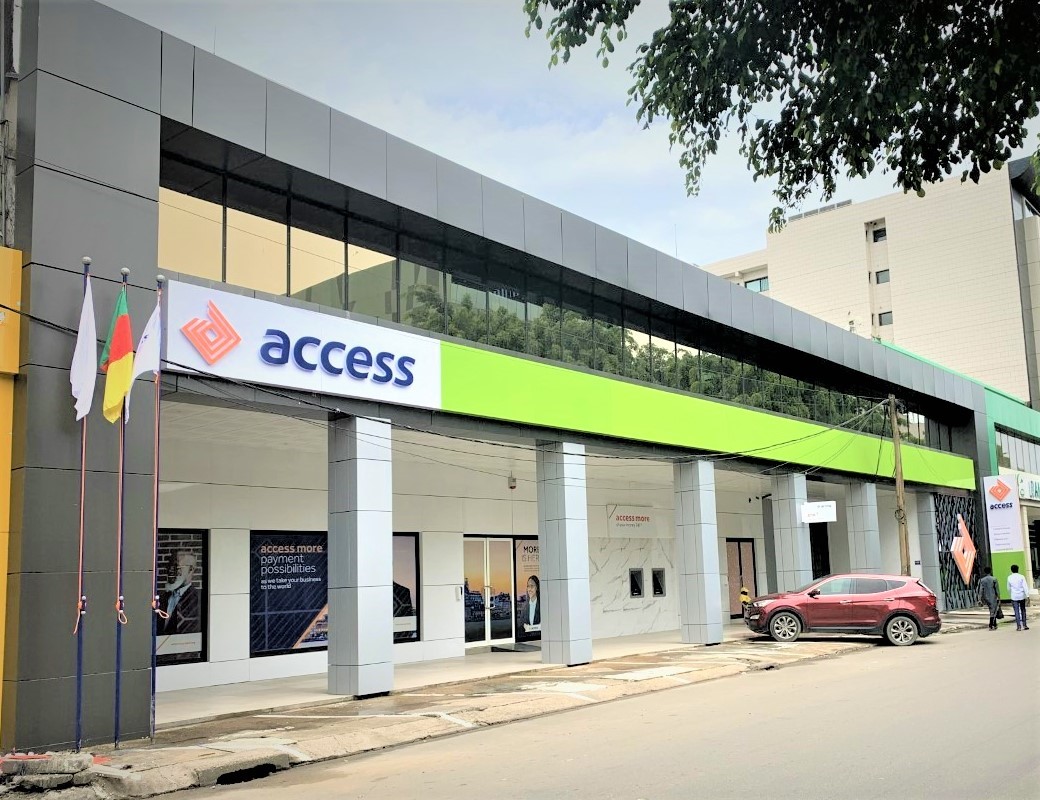
Access Holdings Plc has come under renewed selling pressure on the Nigerian Exchange, shedding nearly 9 per cent of its market value in seven trading sessions as investors reassess the quality of its earnings, rising operating costs and prolonged absence of dividend payments
The shares of Access Holdings Plc, the parent company of Access Bank, have weakened amid growing investor caution, reflecting concerns that the group’s expanding balance sheet is yet to translate into sufficiently strong operating returns.
Market data showed that the stock fell from a seven-session high of ₦29.50 to ₦26.50 per share at Friday’s close, representing a decline of about 10.2 per cent. Another market assessment put the closing price at ₦26.90, indicating an 8.81 per cent decline over the period.
The sell-off reduced the market capitalisation of Nigeria’s largest banking group by total assets to approximately ₦1.46 trillion, based on 54.375 billion outstanding shares.
The decline underscores the growing disconnect between the group’s substantial asset base and its valuation on the Nigerian bourse, where investors appear increasingly reluctant to reward its earnings performance without stronger evidence of sustainable profitability and improved shareholder returns.
One of the issues weighing on investor sentiment is the group’s dividend record. Access Holdings last distributed dividends in 2024, with its most recent payment reported at 2.05 kobo per share, compared with 150 kobo in 2022. The absence of distributions over the past two years has weakened an important attraction for income-focused investors.
Although some equity analysts see considerable upside potential in the stock at its current valuation, the market appears to be demanding more convincing evidence of earnings strength and a credible dividend policy before reassessing the company’s prospects.
Access Holdings’ unaudited nine-month results for the 2026 financial year offer a mixed picture. Profit after tax increased by 5.95 per cent year on year to ₦474.17 billion, but the improvement was supported substantially by a sharp reduction in impairment charges rather than a meaningful strengthening of core operating performance.
Gross earnings rose by 2.28 per cent to ₦3.99 trillion, while net interest income increased by a modest 2.74 per cent to ₦1.29 trillion.
However, the growth in interest income was outpaced by rising funding costs. Interest income increased by 6.91 per cent, while interest expenses climbed by 10.09 per cent to ₦1.81 trillion, highlighting the pressure on the group’s ability to convert lending and investment activities into stronger net interest earnings.
Non-interest income provided some relief. Net fees and commissions advanced by 12.40 per cent to ₦534.94 billion, while other operating income increased by 14.36 per cent to ₦160.66 billion.
Nevertheless, net foreign exchange gains and fair-value hedge income plunged by 73.96 per cent to ₦66.51 billion, contributing to a 3.21 per cent decline in operating income to ₦2.06 trillion.
The pressure was compounded by rising operating expenses, which increased by 11.81 per cent to ₦1.30 trillion. Staff costs rose by 20.51 per cent, while depreciation and amortisation increased by 22.90 per cent.
Consequently, profit before impairment charges and tax fell by 21.32 per cent to ₦760.27 billion, while the group’s cost-to-income ratio deteriorated to 63 per cent from 55 per cent.
The improvement in bottom-line earnings came largely from a 73.45 per cent reduction in loan provisions and impairment charges to ₦92.91 billion. This helped lift profit before tax by 8.29 per cent to ₦667.36 billion.
However, higher taxation moderated the gains. Income tax expenses increased by 14.52 per cent to ₦193.20 billion, limiting the growth in net profit.
The group’s balance sheet expanded moderately during the period. Total assets increased by 1.73 per cent to ₦52.60 trillion from December 2025, while loans and advances grew by 4.53 per cent to ₦16.98 trillion.
Investment securities, however, declined by 2.83 per cent to ₦15.84 trillion.
According to Cowry Asset Securities Limited, managed funds expanded by 6.92 per cent to ₦40.94 trillion, suggesting growth in the group’s funding base. Borrowed funds, meanwhile, contracted by 30.43 per cent to ₦2.05 trillion.
Shareholders’ equity remained broadly stable at ₦4.49 trillion, representing a marginal 0.17 per cent increase, while total liabilities rose by 1.88 per cent to ₦48.12 trillion.
There were also improvements in some asset-quality indicators. The loan-loss provision ratio declined to 0.5 per cent from 2.2 per cent, while the loan-to-deposit ratio eased to 41.5 per cent from 42.4 per cent.
Despite these improvements, analysts remain concerned about the sustainability of the group’s earnings growth.
In its assessment, Cowry Asset Securities Limited said the reduction in impairment charges and borrowed funds was positive but cautioned that weak net interest income growth and rising operating costs pointed to persistent challenges in converting balance-sheet expansion into stronger operating returns.
The research firm also highlighted the modest 0.25 per cent increase in earnings per share to ₦8.02 and the decline in return on assets to 0.82 per cent as evidence that profitability remained relatively subdued.
For investors, the immediate concern is therefore not simply the size of Access Holdings’ balance sheet or its position in Nigeria’s banking industry, but the quality and sustainability of the earnings generated from those assets.
With a market capitalisation of less than ₦1.5 trillion against net assets of approximately ₦4.49 trillion, the group’s valuation appears deeply discounted relative to its reported equity base.
Such a disparity may attract value-oriented investors looking for opportunities in undervalued banking stocks. However, it also reflects the market’s demand for stronger operating performance, better cost discipline and a more predictable shareholder distribution policy.
Until these concerns are addressed, Access Holdings may find it difficult to restore investor confidence, even as its substantial asset base and position in the financial services industry continue to offer long-term strategic advantages.